When we published the Air Outlook 2026, we flagged geopolitical wild cards as a key risk. On 28 February, one arrived. Military strikes closed Gulf airspace and removed about 12% of global air cargo capacity overnight.
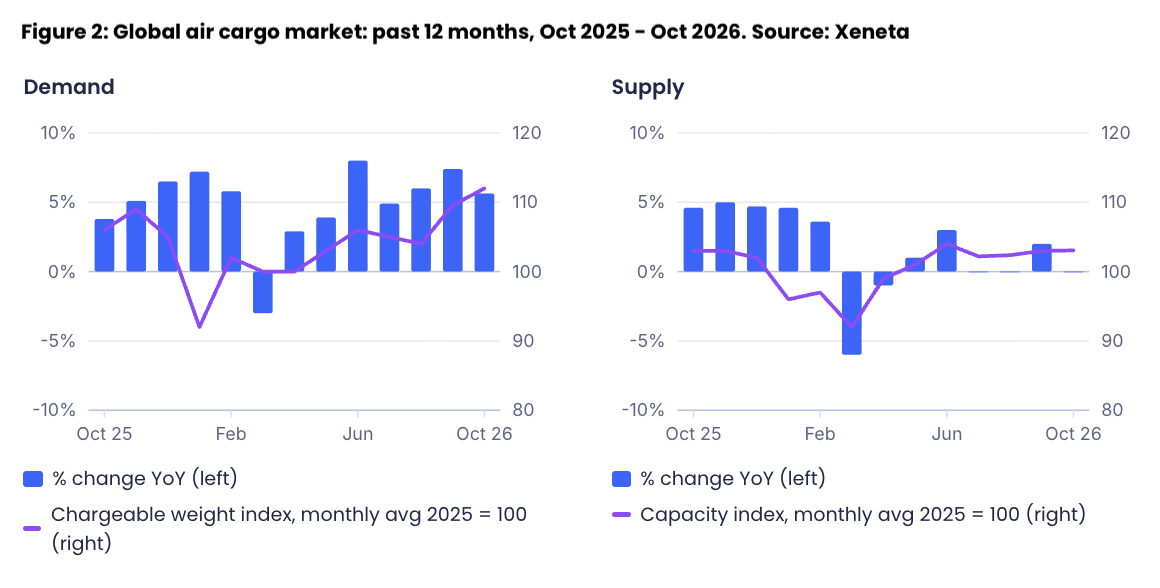
What impressed us most was how quickly the industry responded. European and Asian carriers flew Asia–Europe direct, and the Gulf carriers rebuilt their networks through the spring. The conflict did not shrink the world's air cargo capacity; it slowed its growth. Global capacity is now 2% larger than a year ago, having grown at 6% before the strikes.
The recovery is not yet complete. Far from it. Eight months on, Gulf-origin capacity is 87% of last year, and the Middle East–Europe corridor sits at 75%.
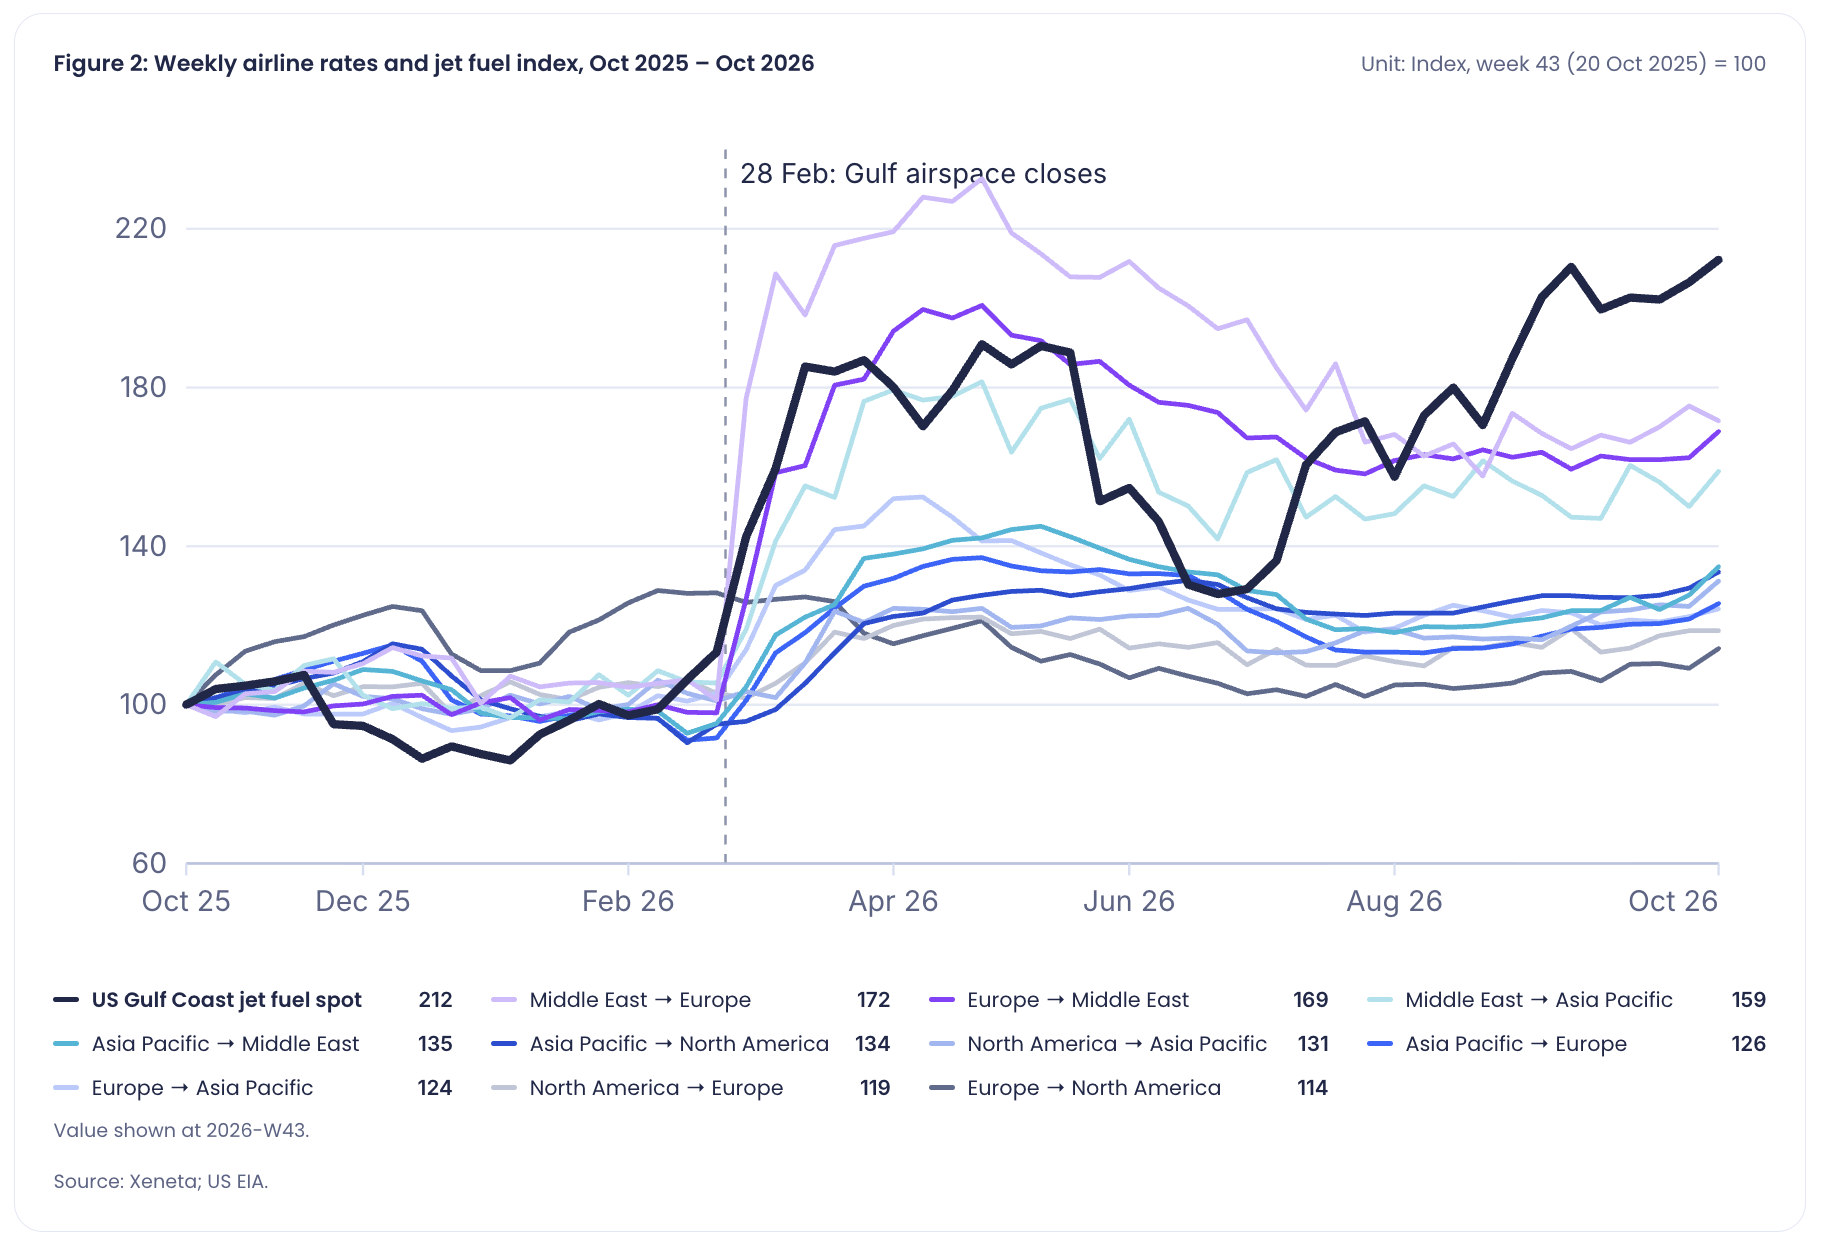
Rates responded directly. Airline average rates into the Middle East were up 48% year on year in October, while most other corridors have given back their March spike.
Fuel doubled, but rates did not follow
Jet fuel costs about twice what it did a year ago. If fuel set the price, every corridor would have followed it up. They didn't. Outside the Middle East, airline average rates are up 14–34%, a fraction of the rise in fuel. On Europe to North America, rates fell 20% into the third quarter even as fuel doubled, because summer passenger schedules brought extra belly capacity.
The corridors with the biggest rate rises were those that lost capacity, not those that burn the most fuel. Fuel sets a floor. Supply and demand on each lane set the price.
Demand keeps growing, but from fewer places
Air cargo demand grew about 5% so far in 2026. It tracked goods trade (+5.4%) rather than GDP (+3.1%). Three extra drivers lifted it: AI hardware, manufacturers building inventory against the war, and ocean disruption that pushed some cargo into the air.
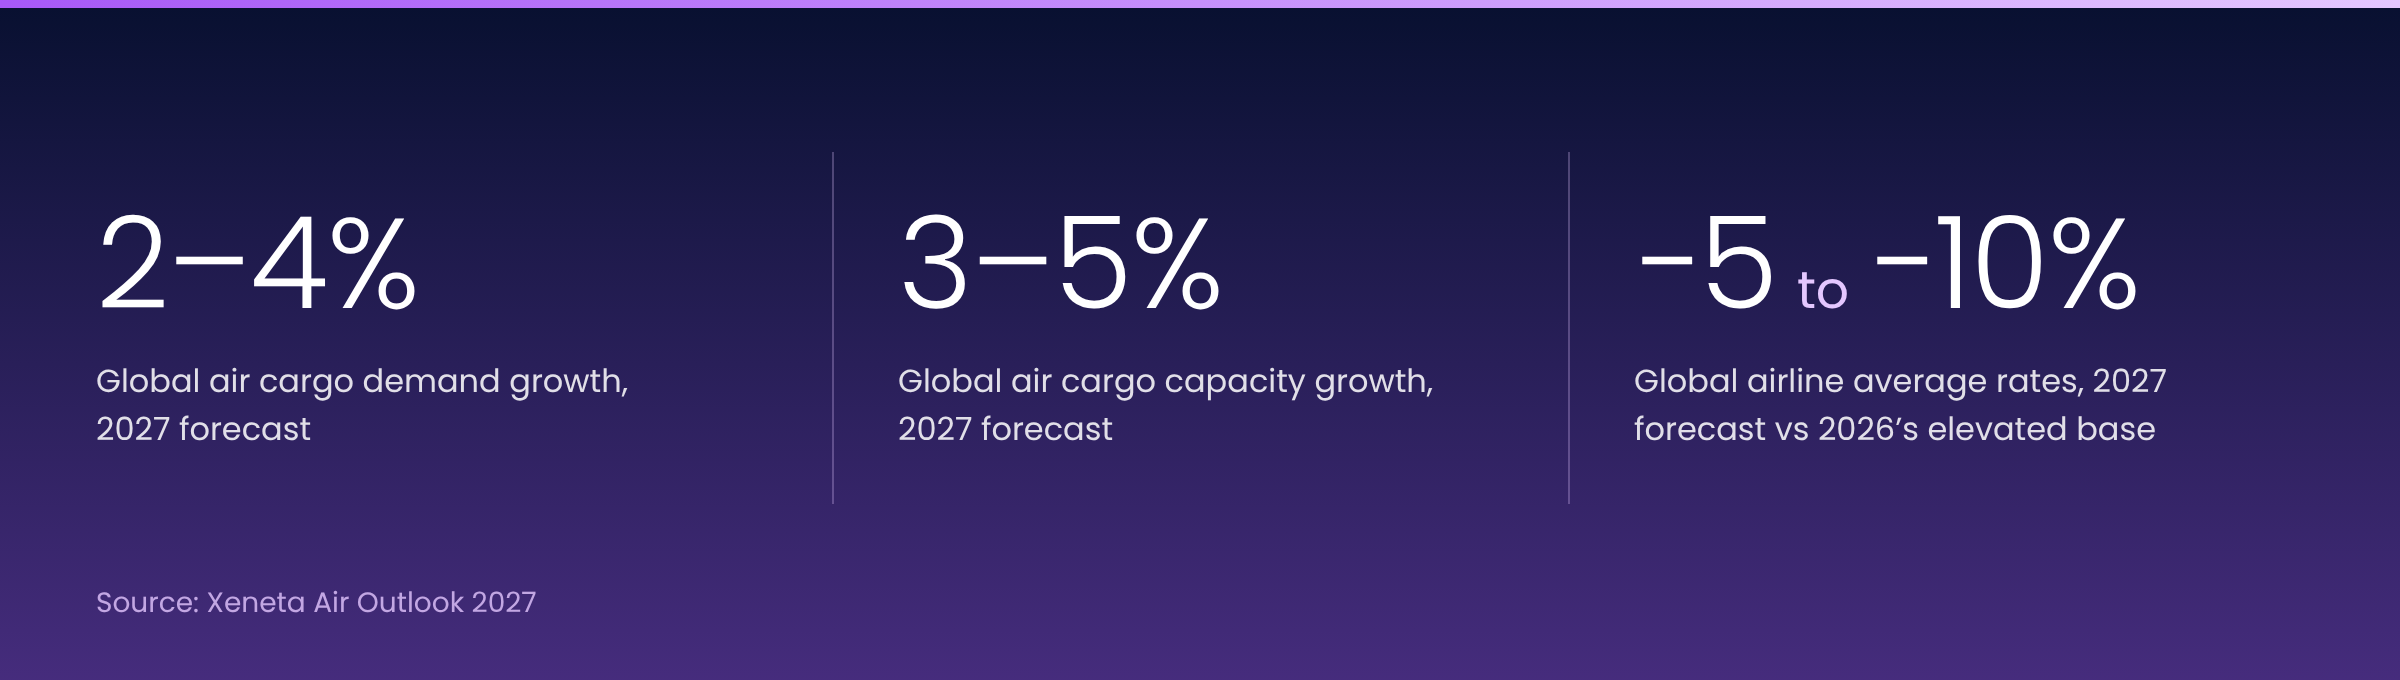
Those boosts are likely to soften in 2027, so we expect demand growth of 2–4%, close to the pace of GDP. Growth is also concentrated. The IMF expects it to come from fewer economies, with AI-hardware and energy exporters gaining while energy importers such as Europe lag. Air cargo will be just as uneven.
Three themes stand out in the full Air Outlook 2027, which is available to Xeneta customers:
-
AI is still the growth engine, but it has passed peak acceleration. Month-on-month chip-sales growth peaked at about 11% in March–June and has eased to about 7%. The effect remains concentrated on Asia Pacific–North America.
-
E-commerce is resetting. China's low-value exports are heading for their first annual fall since 2018 after Europe introduced a €3 duty per item. Consumers are still buying, but platforms are changing how the goods arrive.
-
Routine cargo starts to return to ocean. Half of pre-crisis Red Sea capacity is already back. If the Suez return continues, Asia–Europe cargo that moved to air for reliability, not speed, starts shifting back to sea from the second quarter. A renewed Houthi threat would put that on hold for a third year.
Supply, not the order book, decides the rate outlook
Beyond the Gulf, there is little new capacity to come. Boeing's 777 freighter line has been halted by a supplier dispute, the 777-8F is now (at least) a 2029 aircraft, and Airbus's A350 freighter will not enter service before the end of 2027. We expect fleet growth of a little over 3%, so anything above that has to come from the Gulf. Where 2027 lands within our 3–5% range depends on whether a peace deal is reached early in the year and holds.
With supply growing faster than demand, we expect global airline average rates to ease 5–10%. Most of the fall comes in the second half, as Gulf capacity returns and fuel eases with it. Rates tend to come down more slowly than they go up, and the premium will last longest on the lanes most starved of capacity. It will be more of a rate slide than a slump.
The risks that override the forecast
The above outlook is our base-case scenario. While it assumes no new shocks, recent history gives little reason for comfort.
The Gulf conflict spread in October, when strikes closed Riyadh's airport and cancelled nearly all departures for more than two weeks, setting back the Gulf's recovery. Cyber attacks on shared airport and logistics systems can halt cargo handling without touching an aircraft.
Weather disruption is a growing risk too. Extreme events are becoming more frequent and more severe as the climate changes, and the US National Oceanic and Atmospheric Administration (NOAA) sees a high chance that El Niño becomes the strongest on record.
If the Middle East fails to recover, supply and demand grow in step, fuel stays high, and rates hold close to 2026 levels.
We should stop calling these events black swans. They happen far too often to hold that title.
What this means for your freight going in to 2027 tender negotiations
A 5–10% fall in the global average is not a 5–10% fall on your lanes.
Asia Pacific–North America is likely to keep more of its premium, because AI cargo is now part of the price of space. Shippers on Asia–Europe have more room to negotiate with forwarders than a year ago.
Contract frameworks matter too. In 2026, a shipper whose contract floated on a fuel index paid more on specific lanes while the forwarder paid less. Timing and terms matter as much as the rate itself: a tender run at the top of the year is priced at the top of the market.
Next steps
This article is the short version. The full Air Outlook 2027 covers six themes in depth, from the global economy and mode shift to e-commerce, AI investment, supply and external disruptions, each with our advice to shippers. It is not published openly, and it is available in full to Xeneta customers.
If you are not yet a customer, book a walkthrough with our Market Intelligence and Advisory team. They will map the forecasts against your lanes, your industry and your 2027 tender timeline.