The end of Q3 knocked global reliability down to 27% on-time as delay climbed to 6.0 days
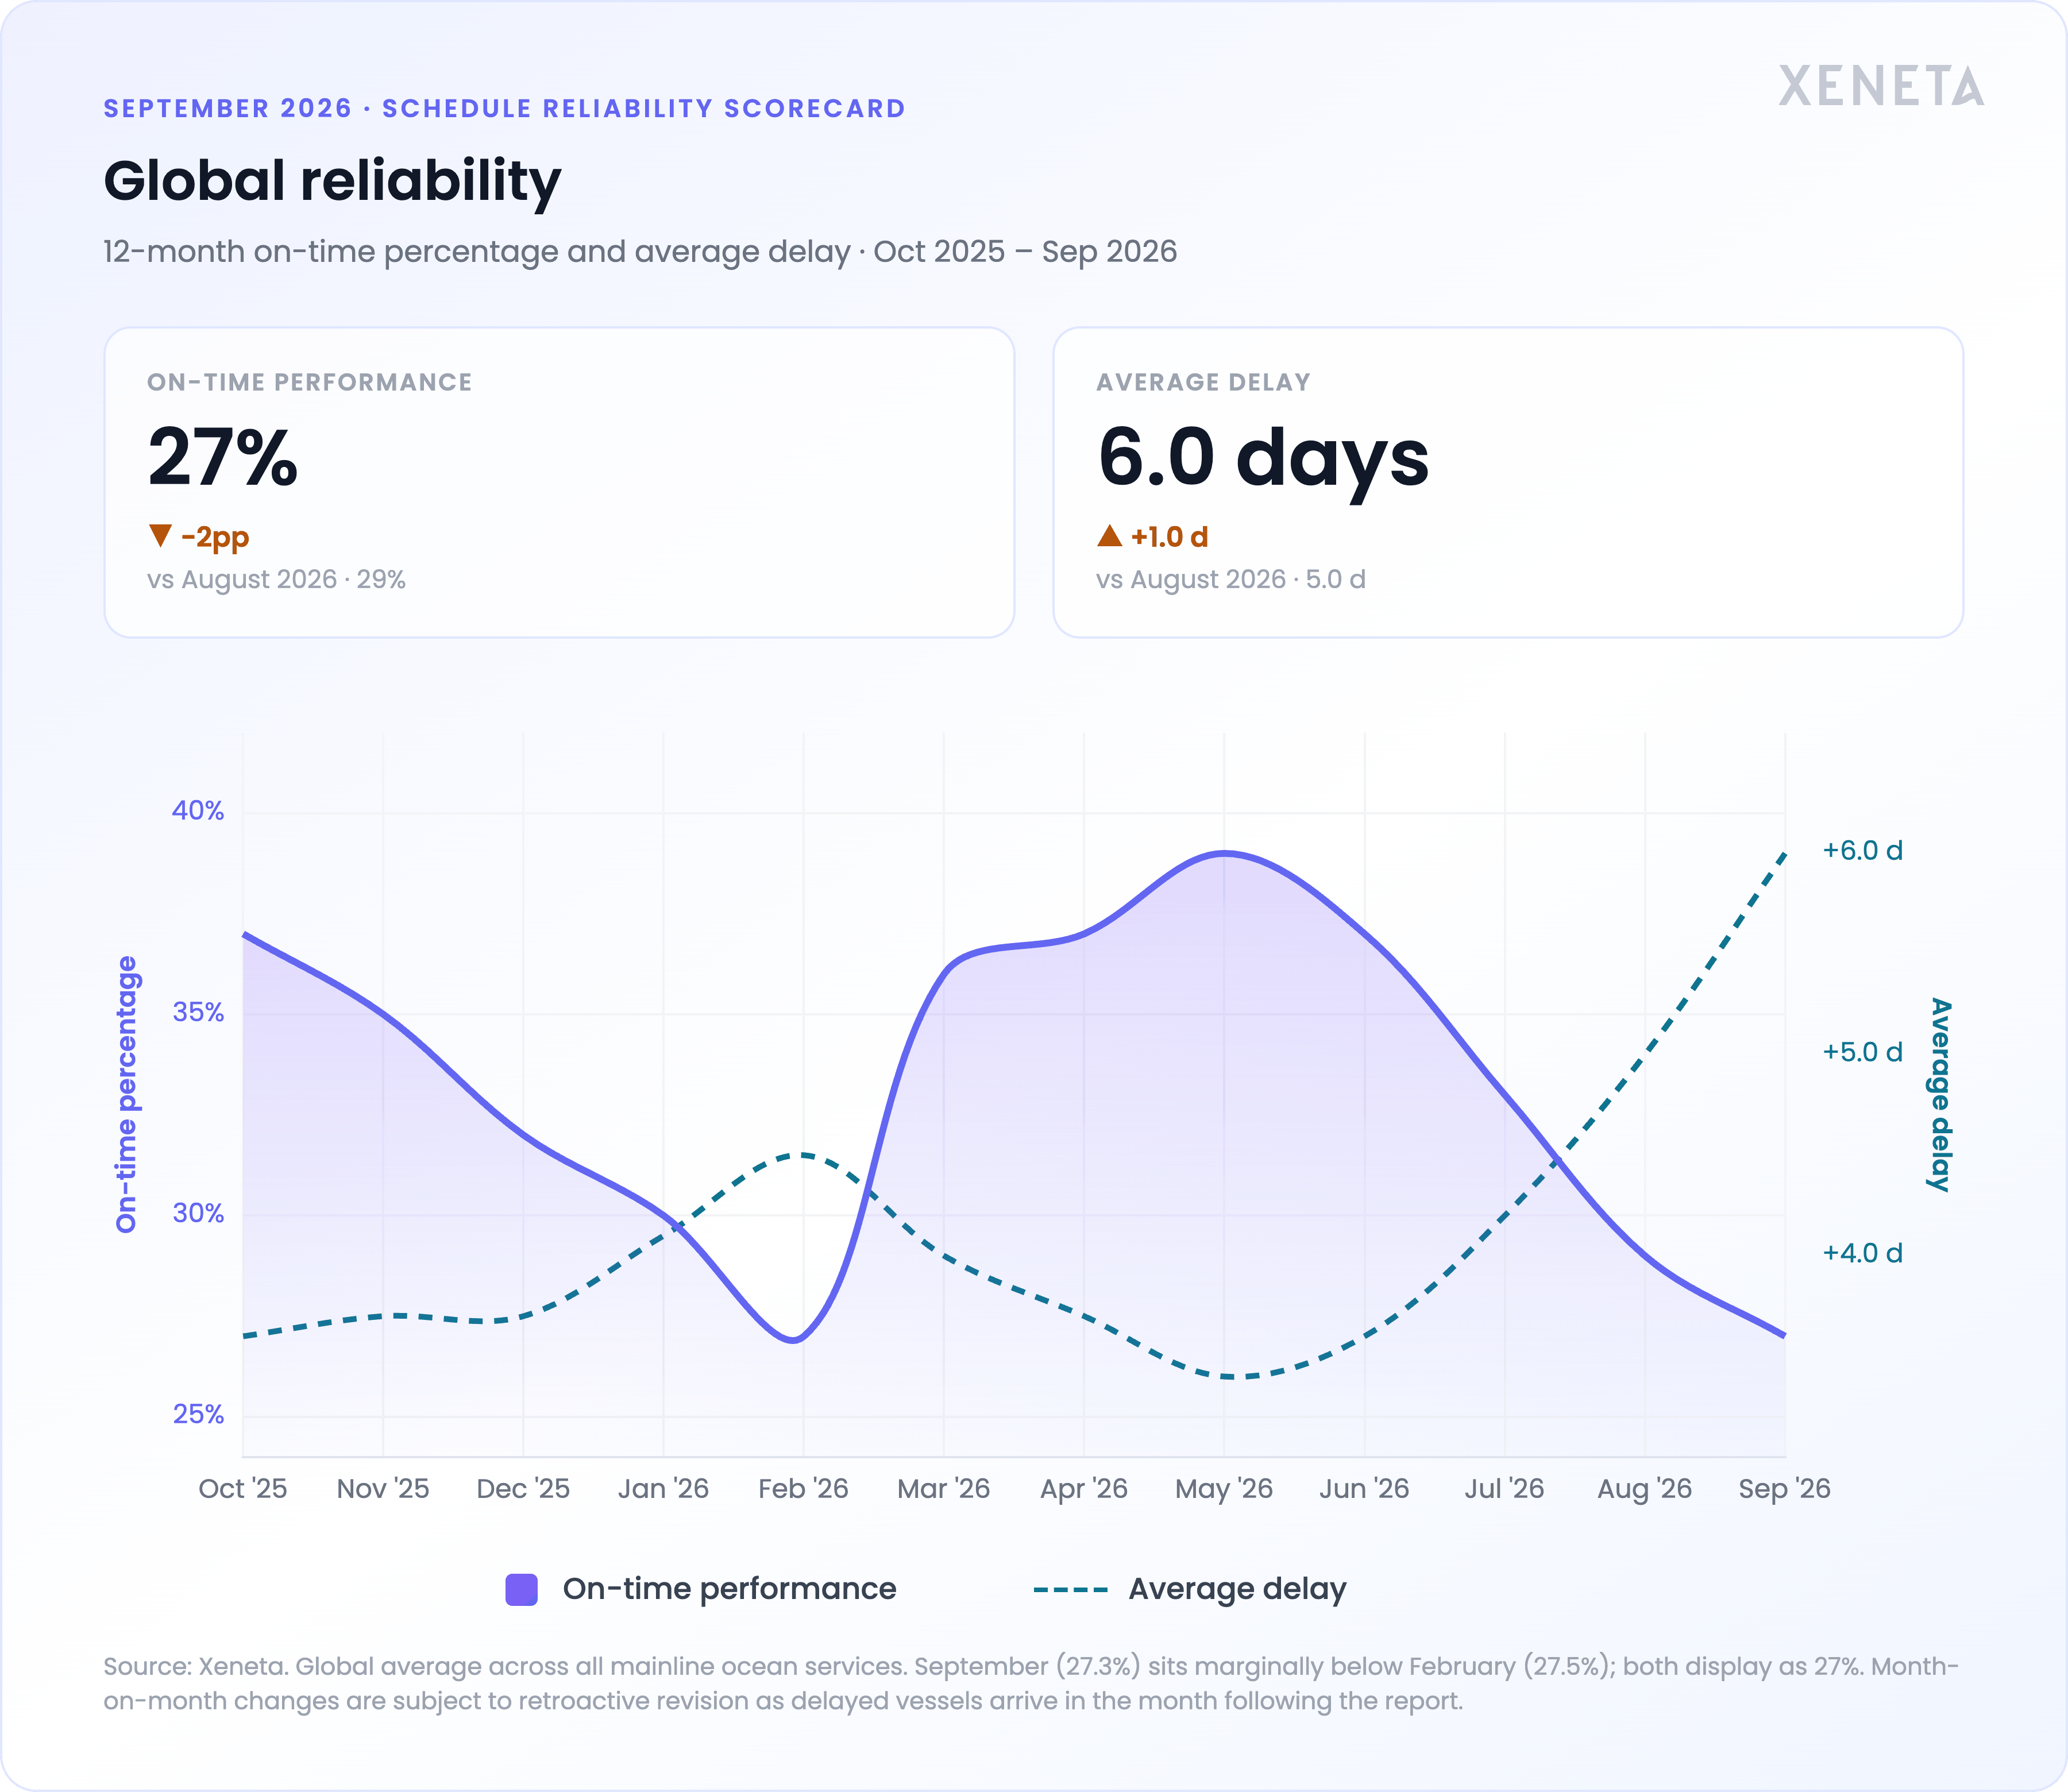
Global reliability fell for the fourth consecutive month down to 27% on-time, 2pp lower than August and now matching February’s floor earlier in the year. There is little prospect of hitting a firm floor in October given continued deterioration on Asian trades following a sequence of powerful typhoons that landed from July through early September.
Average vessel delay increased in step, rising for four consecutive months up to a 6.0 day average across all arrivals and a total 2.4 day rise since the beginning of Q2.
Trades: Far East to Europe collapsed to 4% on-time as Asia-linked trades hit 12-month lows
This month’s trade reliability splits sharply by geography: Asia-linked trades sit at or near 12-month lows of on-time arrivals and 12-month highs on average delay. The compound effect of typhoons on existing constraints insists that the right combination of circumstances can continue to eat away at global reliability months after the fact and far from the original localization.
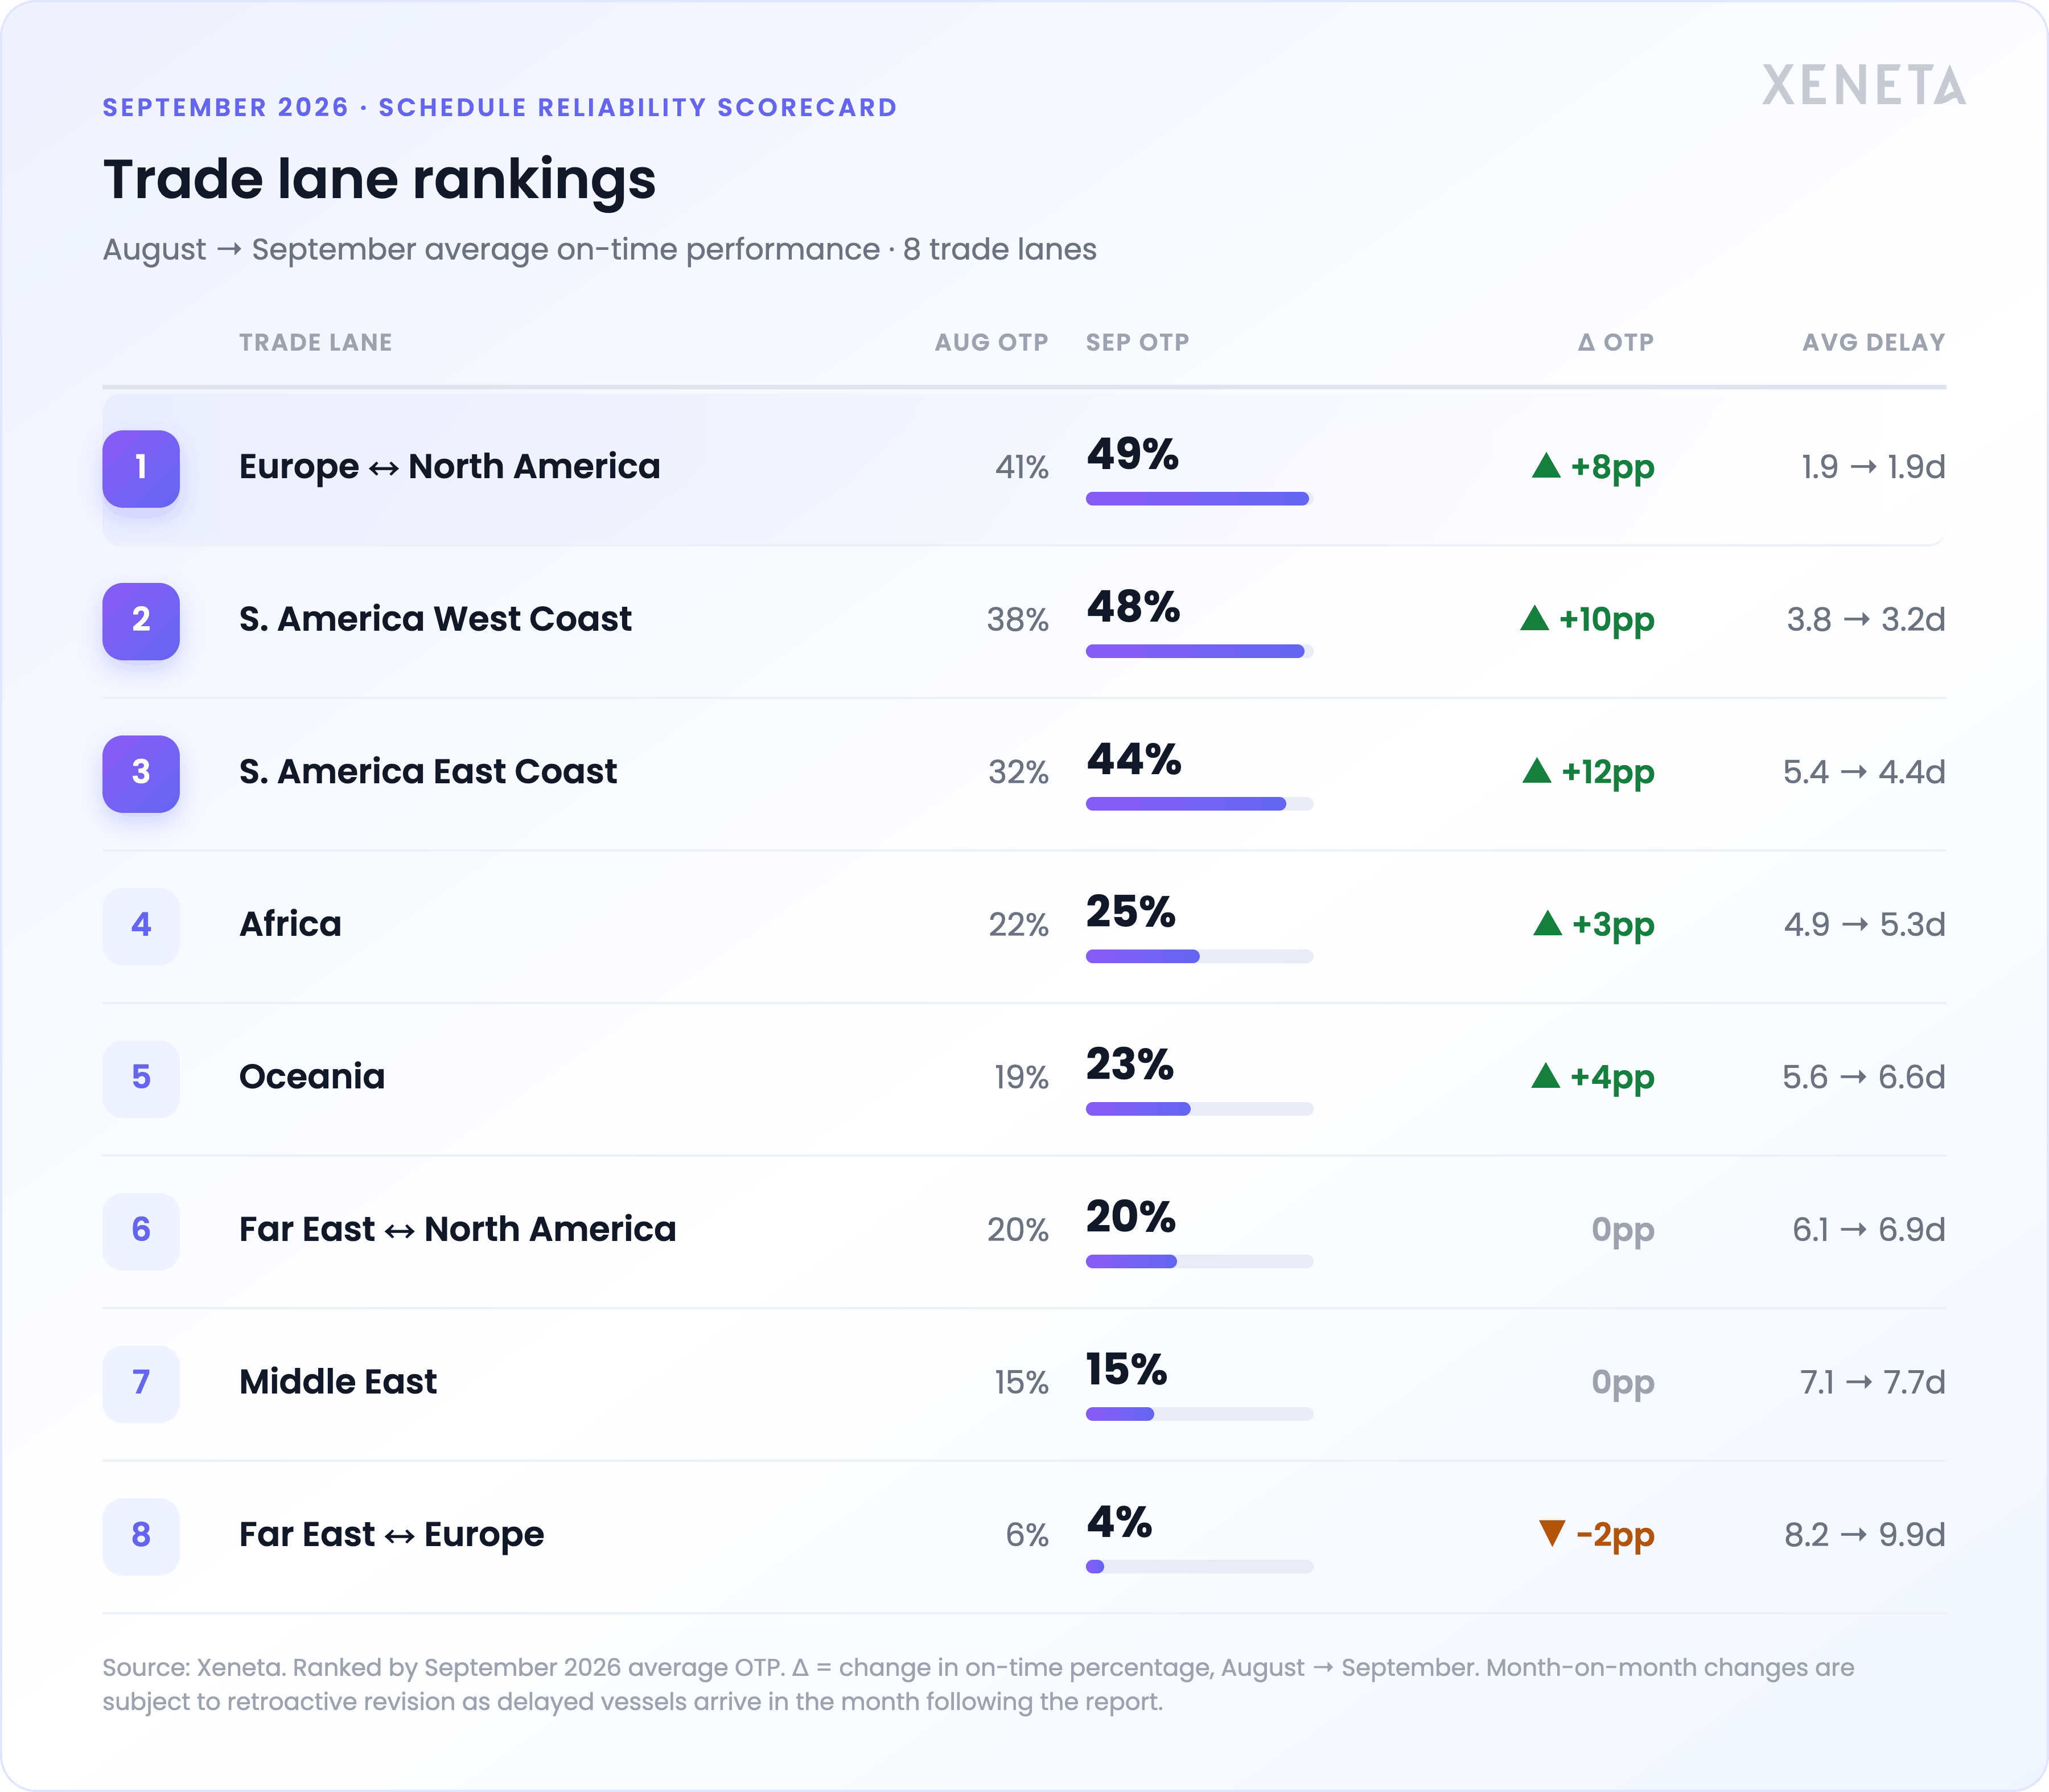
Far East to Europe nose-dived to 4% on-time with a stunning 9.9 days of average delay across all vessels, its worst month since September 2021 when it hit 3% on-time. Far East to North America held flat at 20% on-time while delay rose by 0.8 days from August to a total of 6.9 days in September.
Rates are following an equally unfavorable path for shippers. Xeneta’s spot market average for China to US West Coast reached $7,717 per FEU in early October, over four times September 2025 ($1,778) and up 8% on the start of September 2026. Long-term rates are catching up from a much lower base, at $3,649 per FEU on 1 October but rising +26% month on month. As Death by a Thousand Paper Cuts explains, no single factor controls the current climate: bunker costs, ongoing typhoon disruption, and a strong peak season have each added to it.
South America West Coast and East Coast were the only trades to improve across both reliability metrics this past month, gaining +10pp and +12pp respectively and cutting average delay by up to 1.0 day. It’s a positive streak in what feels like an uncompromising environment, and good timing as there is little slack left to absorb delays going into Brazil’s peak export season.
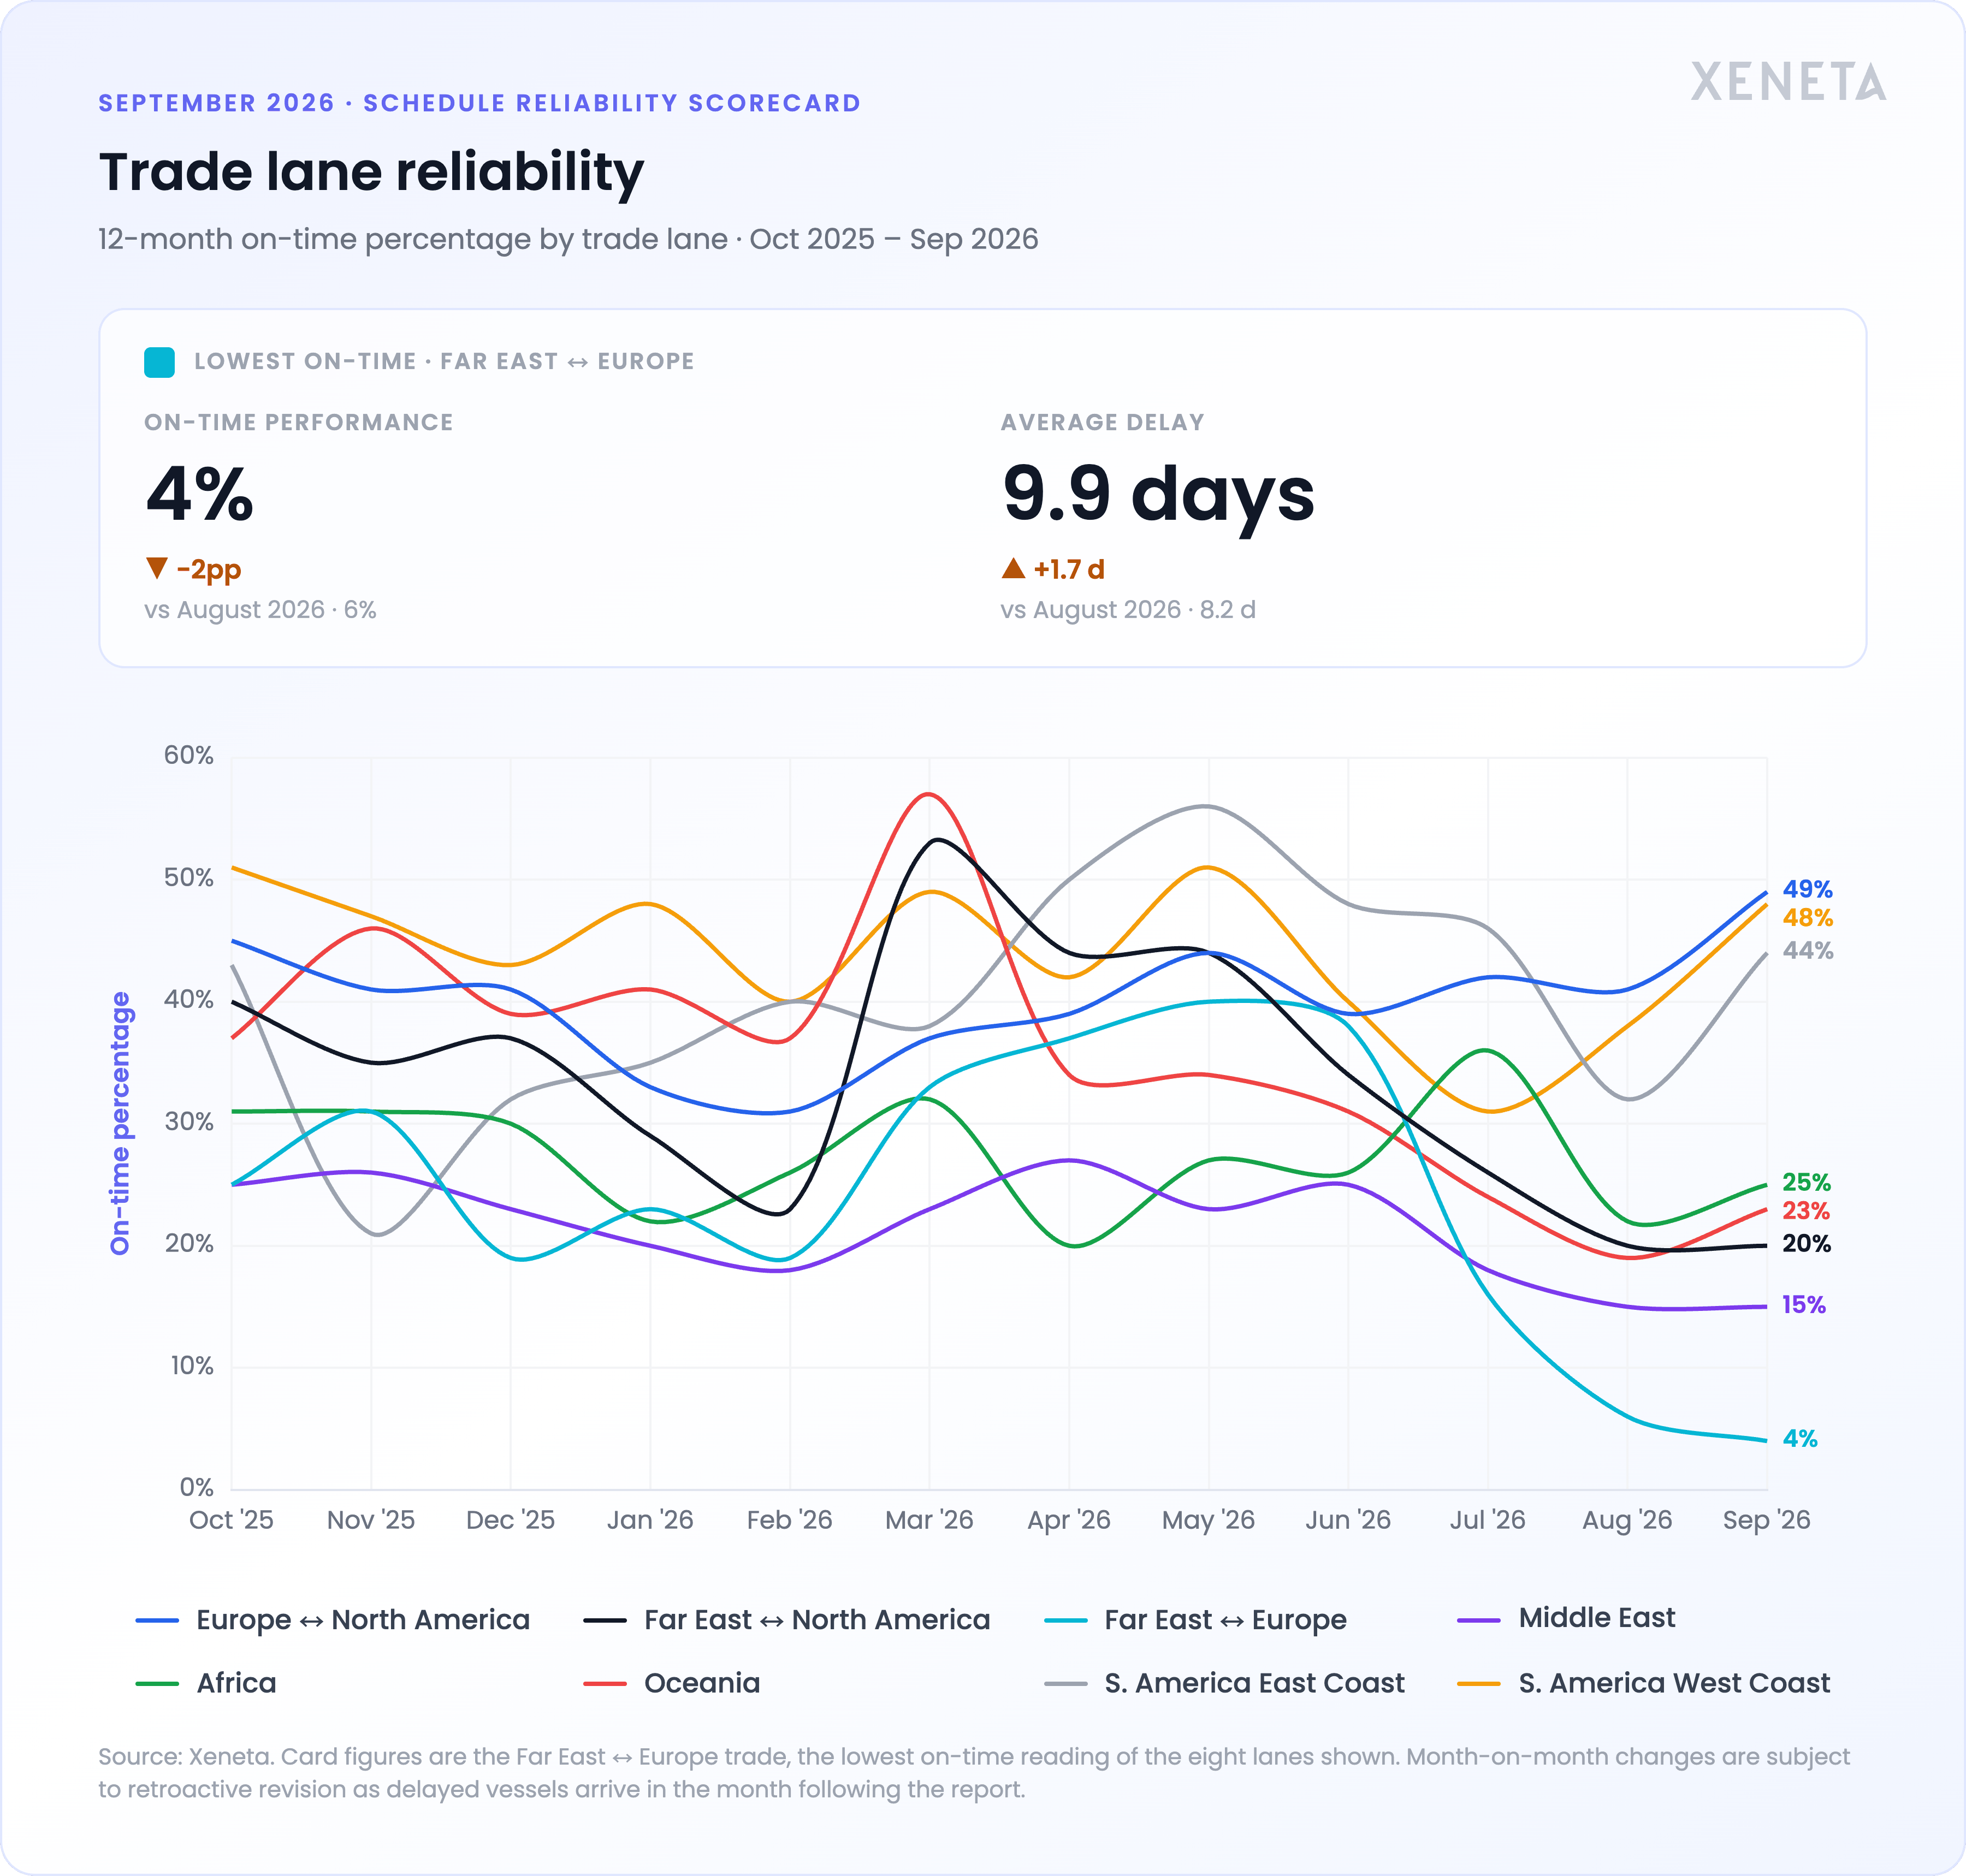
On the upper end of the spectrum, Europe to North America led for the second month running, outpacing South America West Coast on +8pp MoM improvement to 49% on-time – its highest since August 2025 – and the lowest average delay of any trade at 1.9 days.
Carriers: Every carrier posted a 12-month delay high as shippers prepare for tenders
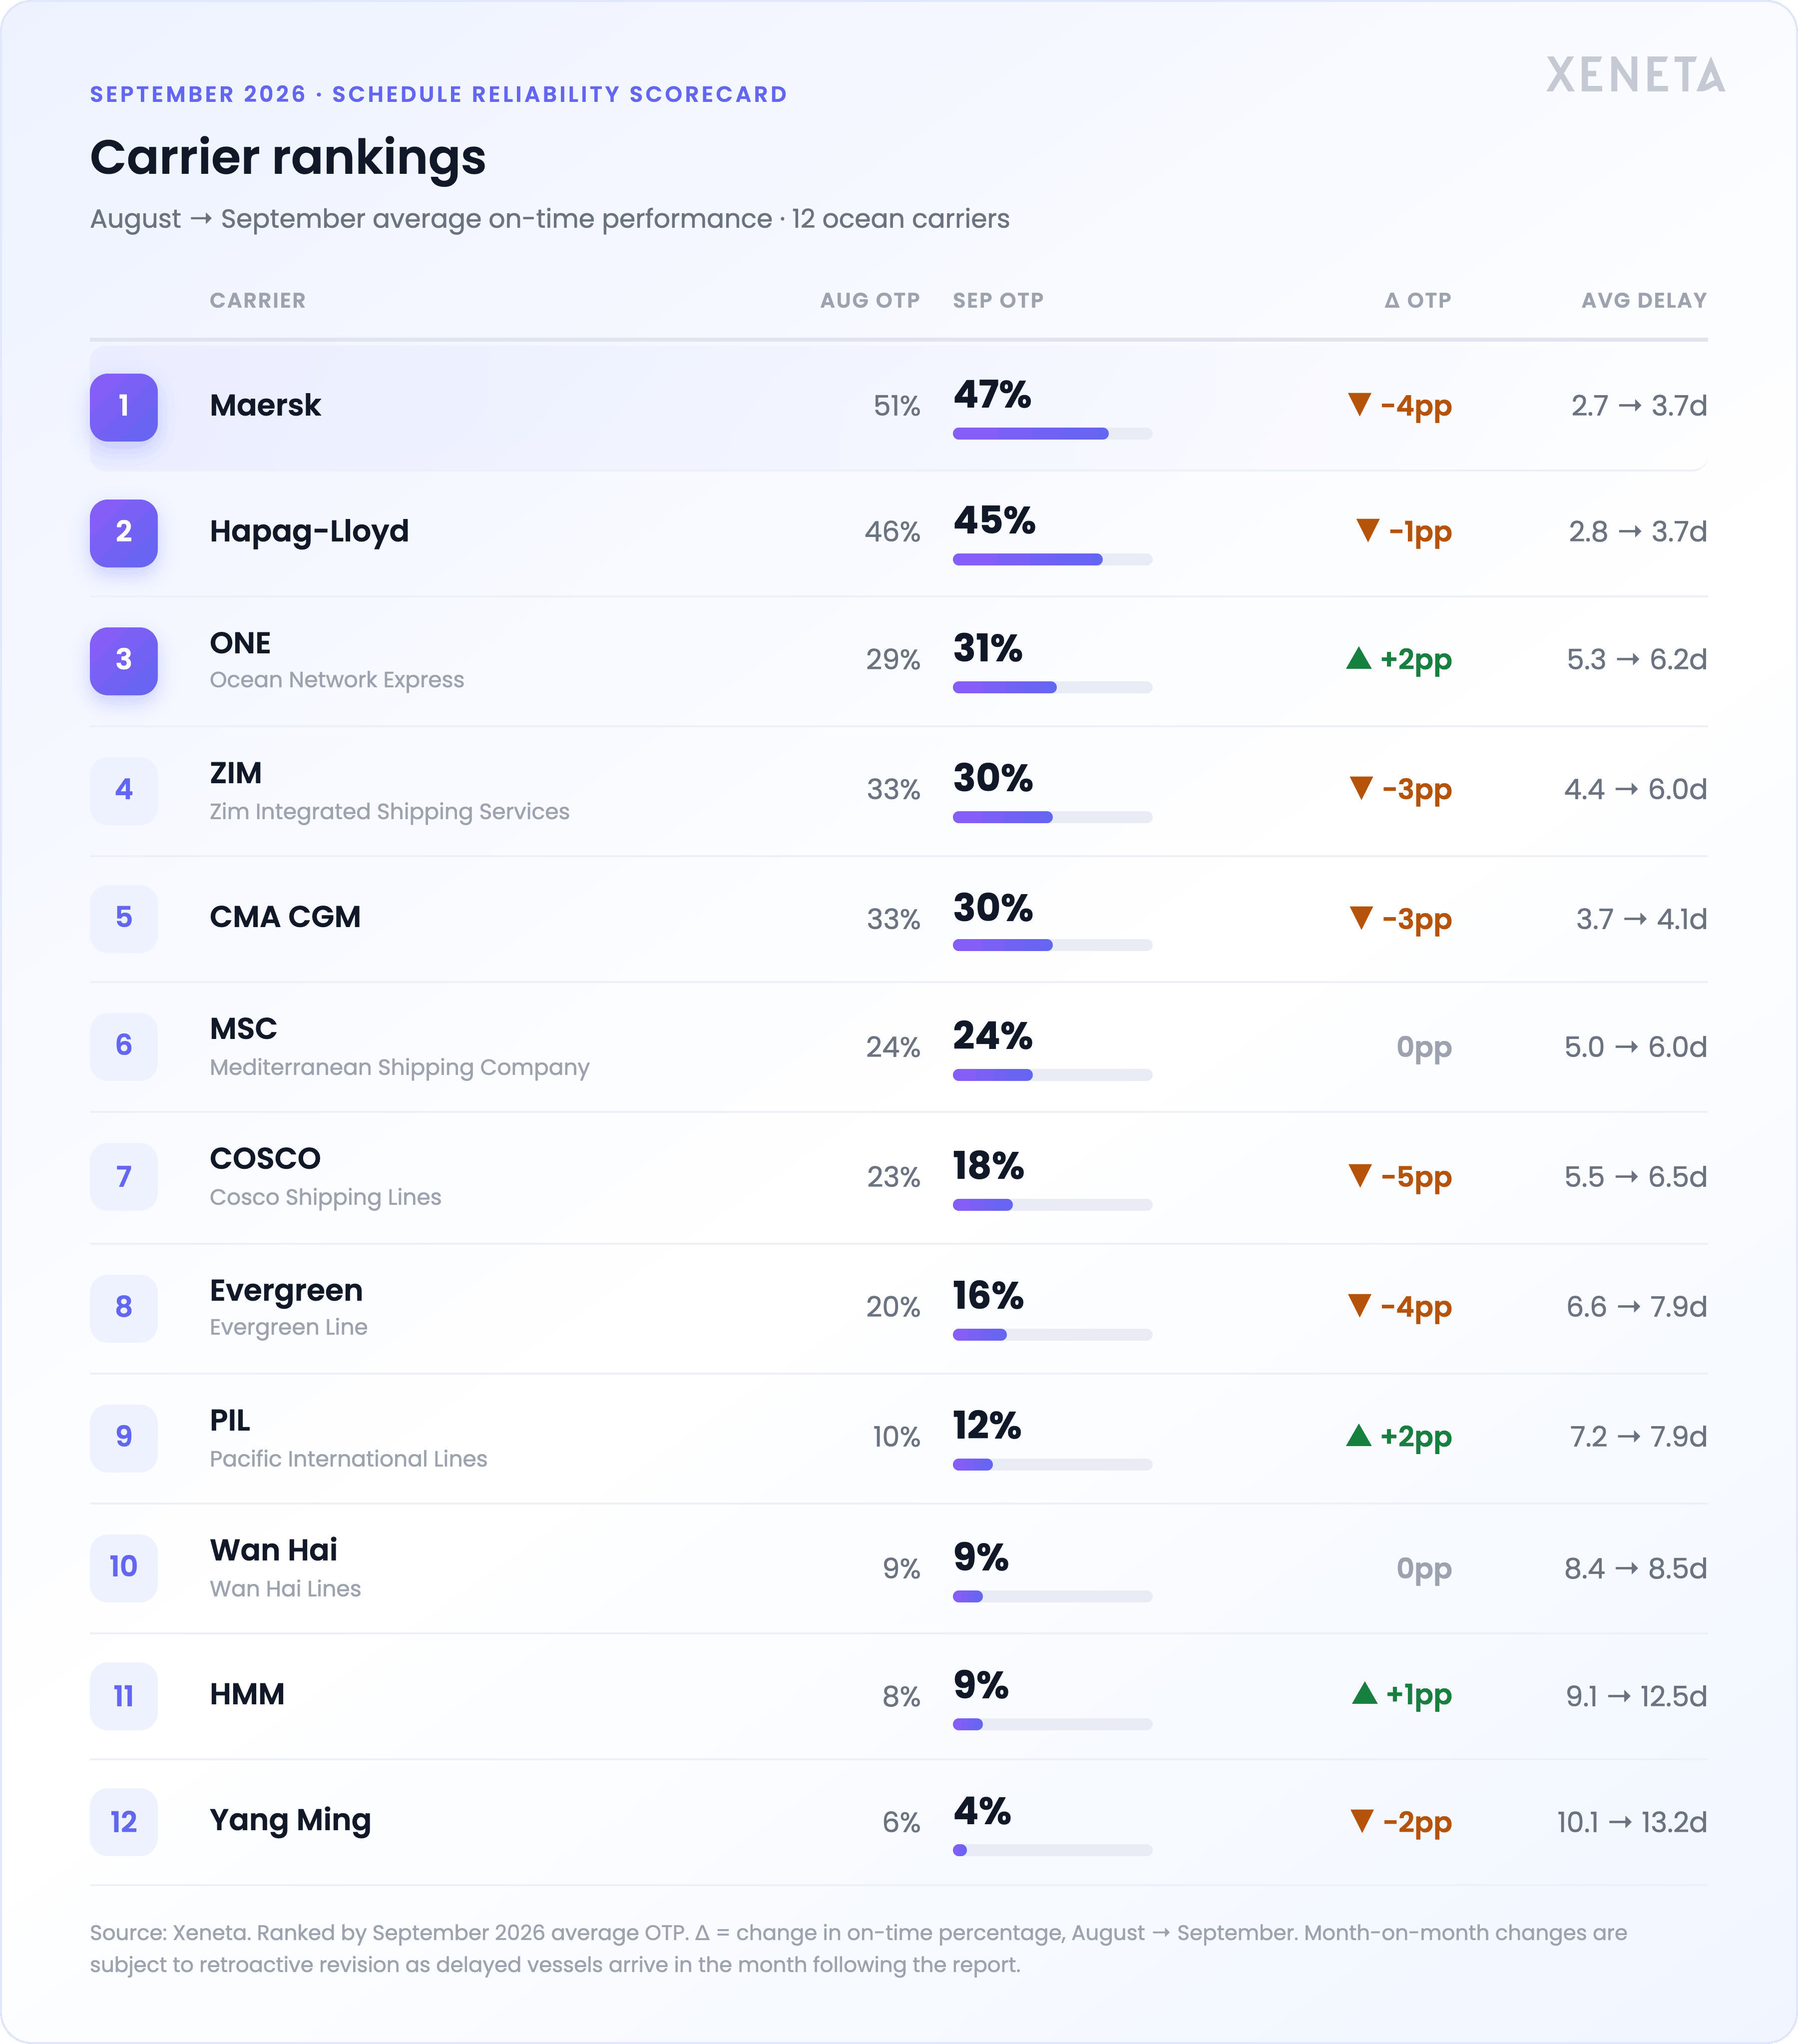
Every carrier posted its highest average delay over the past 12 months in September, but only four hit a 12-month low in on-time arrivals: CMA CGM (30%), Cosco (18%), Hapag-Lloyd (45%) and Yang Ming (4%).
The increased risk lies in severity rather than the frequency of late arrivals. Buffer days in contracts and inventory plans are being consumed at an alarming rate, and the ongoing deterioration means any contingency plans set in motion today may not hold up when your next booking arrives.
The spread between carriers continues to compress, from 45pp in August to 43pp this month. While the on-time floor fell as Yang Ming hit 4%, the ceiling came down as Maersk fell from 51% to 47%. Leaders are falling as opposed to underperformers catching up; holding carriers charging a premium for service reliability accountable is a must for shippers going into 2027 tenders.
Both Gemini partners have declined MoM for the past five months, and the Gemini network has fallen harder than other alliances, from 70% on-time in June to 40% in September. A weekly perspective shows how severely the tail-end of typhoon delays stacked up out of Asia: from 62% in the first week of August down to 34% by the week of 28 September.
Port Congestion: Singapore’s queue doubles as Chinese port delays spill into Southeast Asia’s transshipment hub
Average vessel wait times in Africa’s ports fell by nearly a full day to 2.5 days in September, and the share of vessels waiting held at 32%, yet the region still leads global congestion. Apart from a modest 0.1-day dip in Northern Europe, Africa was the only region to improve.
Southeast Asia follows at 2.0 days of average vessel wait, edging past the Middle East, with the share of vessels waiting increasing up to 23%. Vessel queues in Singapore nearly doubled from 12 to 22 vessels per day at 29% and average wait spiked from 1.9 to 3.1 days as it continued to absorb downstream effects from Chinese port congestion.
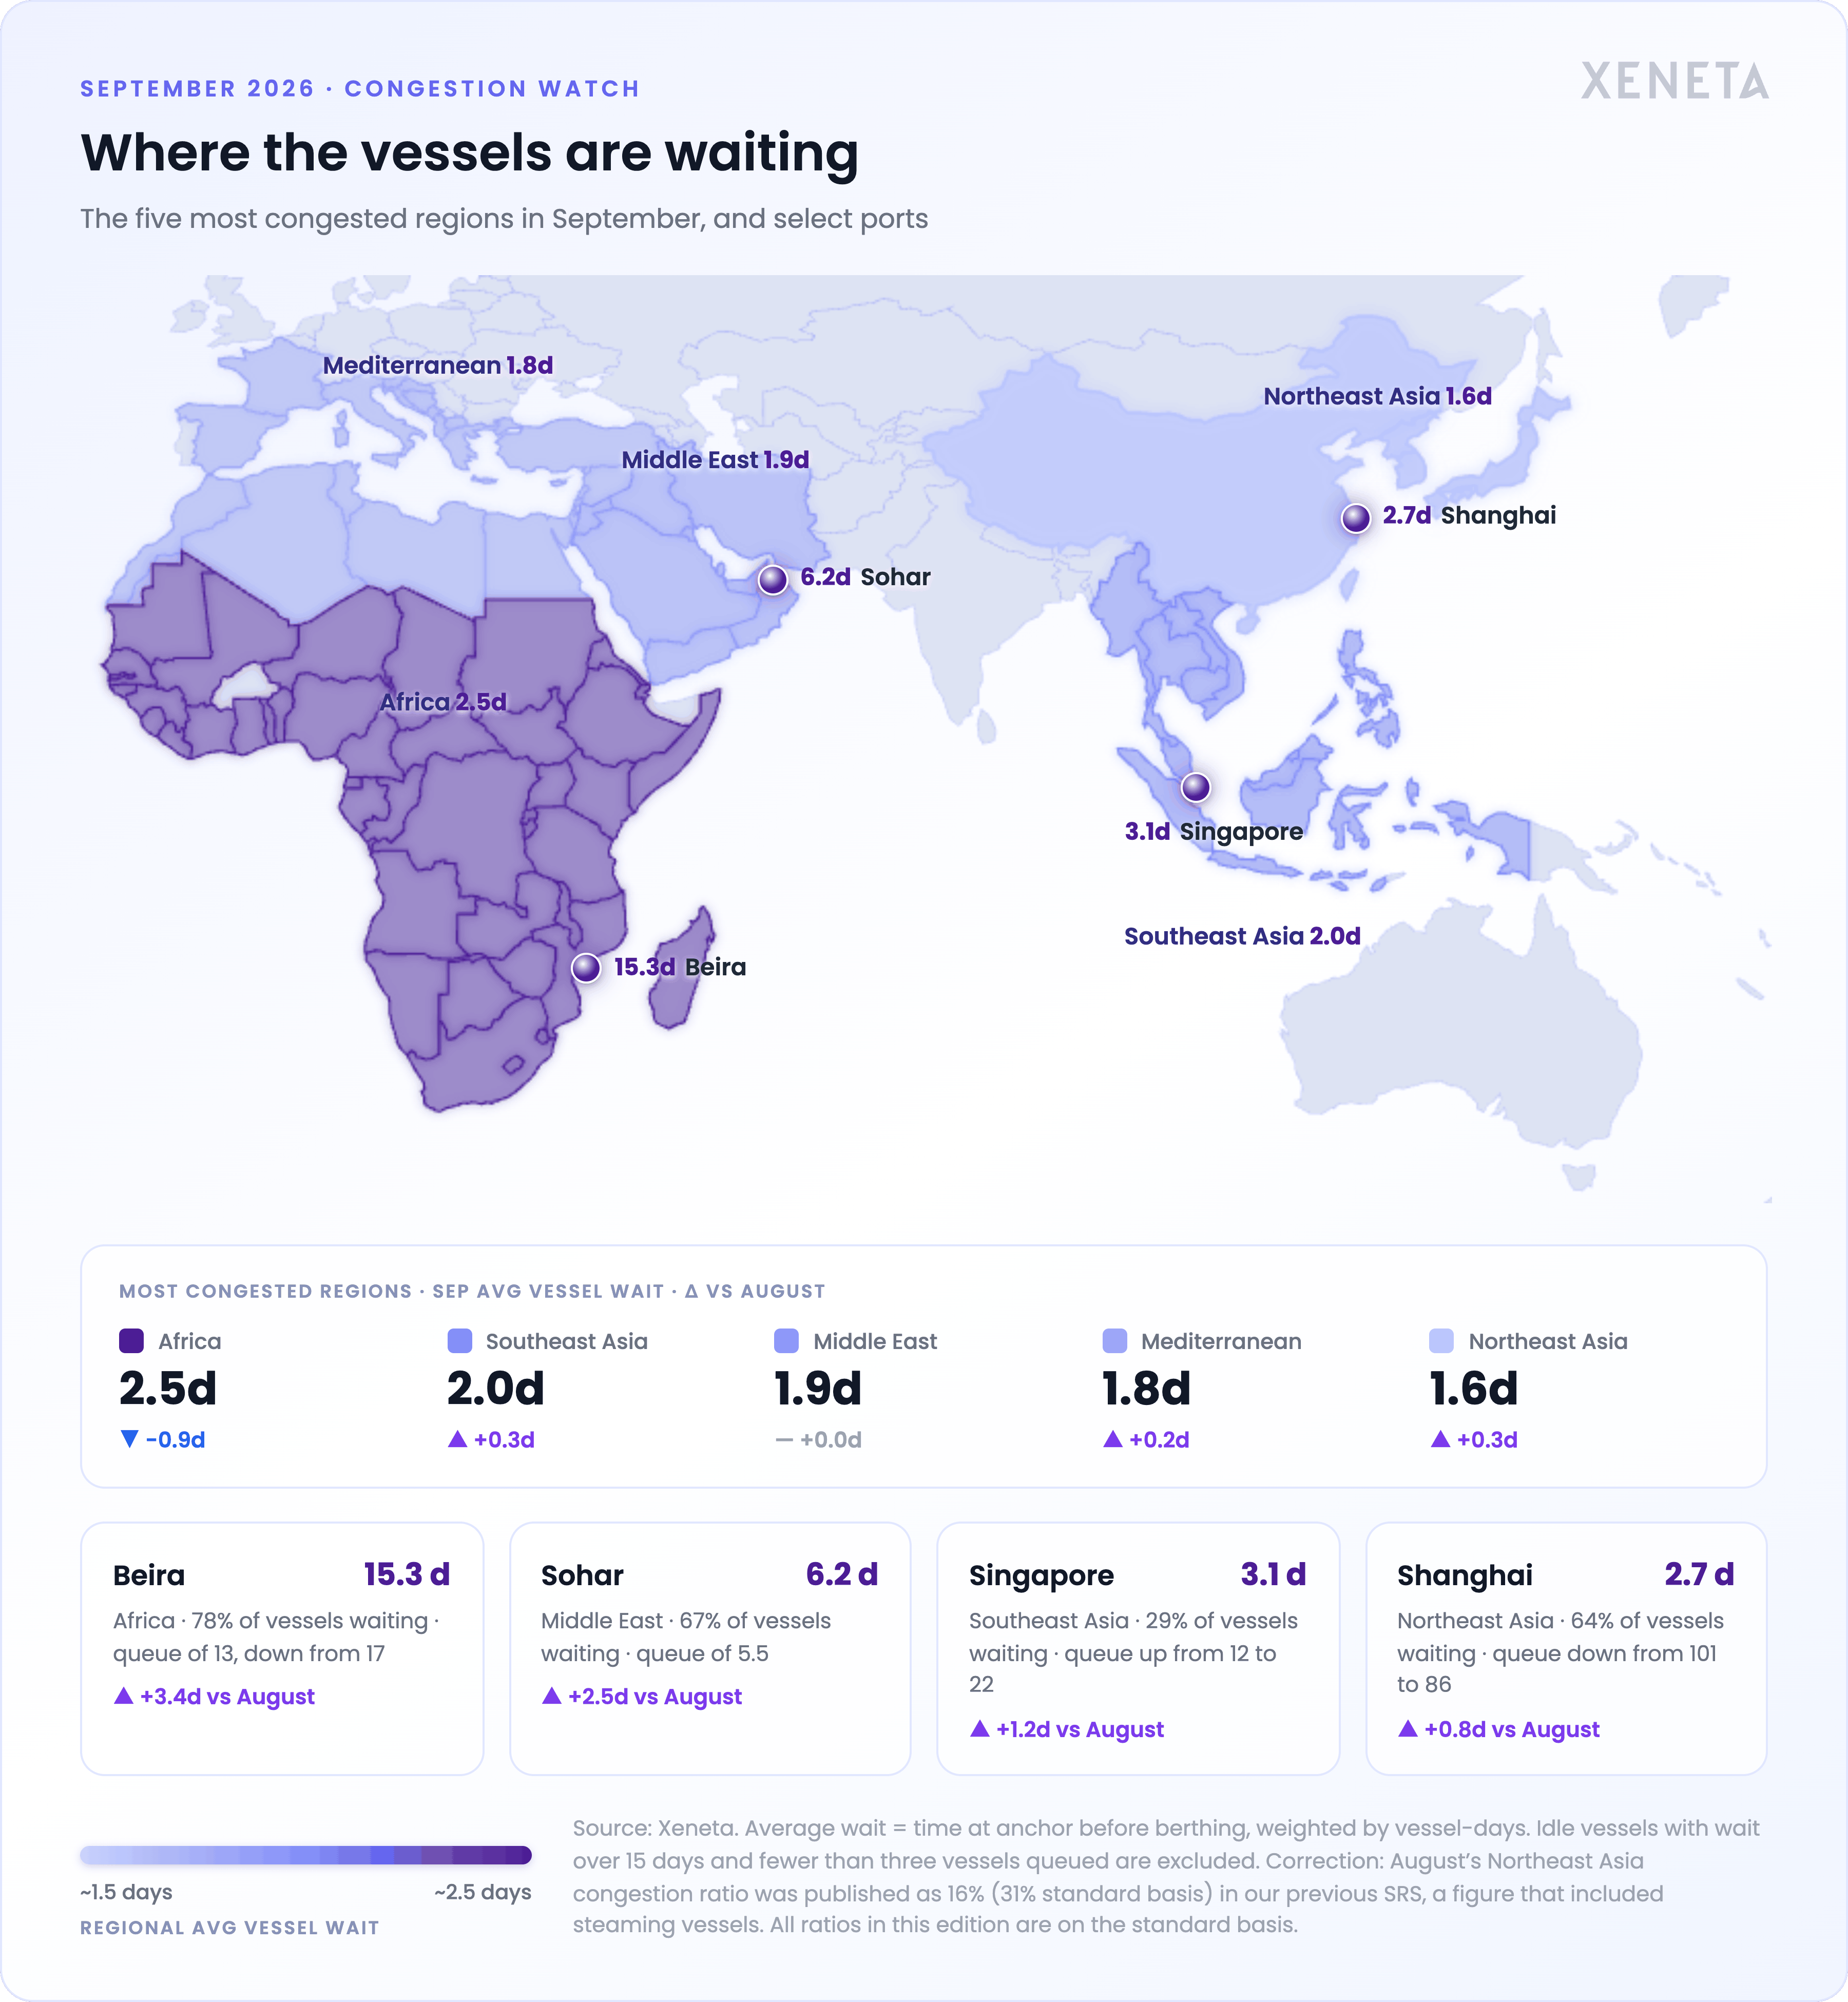
The Middle East held flat across both vessel wait times at 1.9 days and the share of vessels waiting at 26%. Smaller gateways such as Sohar continue to feel the strain of functioning as pressure valves for the Strait of Hormuz, absorbing over 180,000 in displaced weekly TEU and less than half of the 423,000 TEU bound for Jebel Ali before the war.
In Northeast Asia, just under a third of vessels at port were waiting in September at 30%, and average wait rose by 0.3 days to 1.6 days total. Waits were shorter than leading congestion in Africa and Southeast Asia, but pressure from the late-summer typhoons and pre-Golden Week demand kept space tight and yards utilization high.
Queues remain long at Chinese ports, and they show up as increasingly severe berth-arrival delays for shippers in North America and Europe. Shanghai is one exception, where the queue shortened from 101 to 86 vessels at anchorage on an average day and wait lengthened from 1.9 to 2.7 days. A short average wait can still hide a long queue and a long wait can sit behind a short one, so shippers should check queue length and wait severity together when assessing congestion impact on their bookings.
Special: Blanks eased in September but carriers are ramping back up
With so much capacity absorbed by delays in September bunching up against pre-Golden Week demand, carriers blanked just 6% of planned capacity on Far East to Europe, the third-lowest share of the past 21 months. On Far East to North America it was 8%, also the third-lowest in the same period.
That said, blanking is stepping up sharply in October to at least 17% of planned capacity on Far East to Europe and 13% on Far East to North America. The announced share is still below October 2025, which could mean carriers are keeping more capacity in rotation to work off the typhoon backlog, or that more cancellations will land in the following weeks.
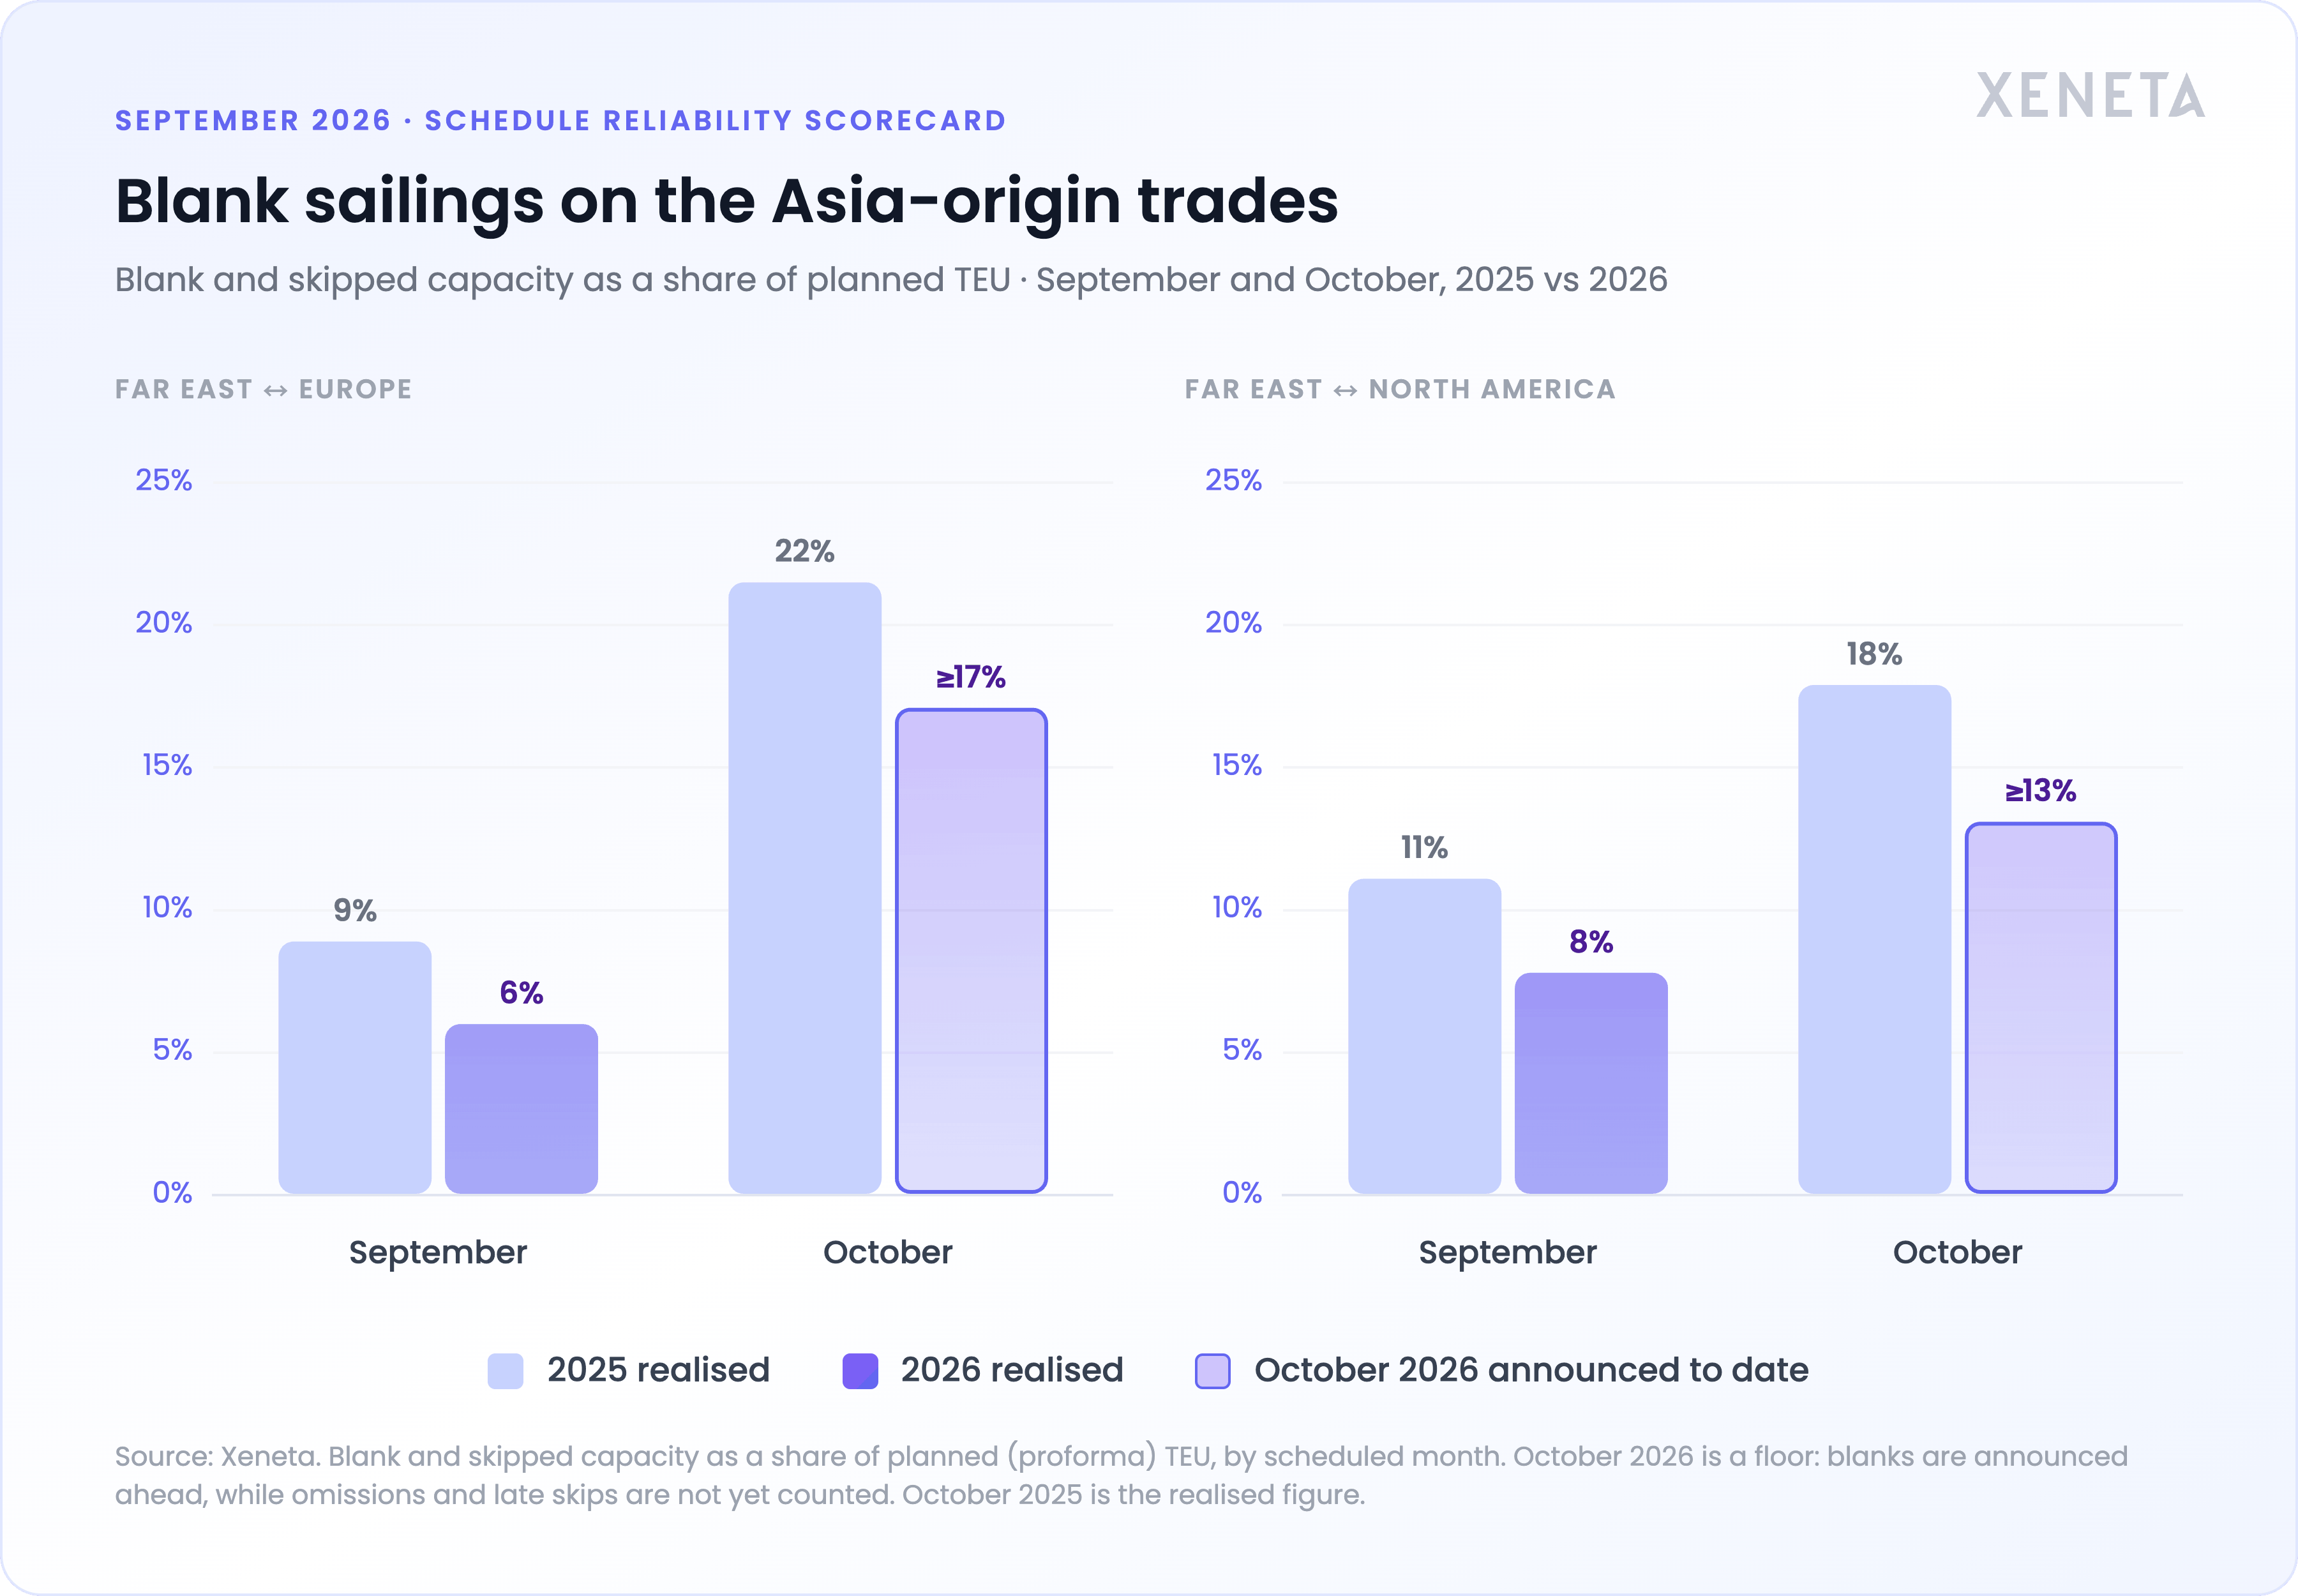
Planned capacity on Far East to Europe in October is the highest of any month in a 22-month window, and Far East to North America’s is third-highest. With more capacity scheduled into Golden Week and a smaller cut compared to 2025, a trade hitting 4% on-time has even less slack to offset delays with voided sailings. For shippers in Europe and North America, that means October bookings should be given more lead time and carriers should be asked which services they are protecting from capacity cuts.
What to watch
-
Gemini has not found a floor. The network’s weekly on-time rate has fallen sharply since early August, and the week of 5 October already reads 28% on partial data. A network with no slack between disruptions may mean Gemini’s reliability advantage over competitors faces a longer road to recovery.
-
Chinese anchorages are clearing, but the disruption is moving downstream, not disappearing. Ningbo and Yantian waits eased in the same month Far East to Europe hit 4%, and the delay is landing at berths in Europe and North America. Shanghai, Ningbo and Yantian still held 0.74 million TEU at anchor as of 6 October.
-
China to US West Coast spot rates sit at more than twice the long-term rate ($7,717 vs $3,649 per FEU). Contracts are repricing upward, so renewals are likely to cost more, and delays now hit shippers’ budgets as well as their lead times.
-
Shippers shouldn't let narratives around port congestion take attention away from carrier accountability. Schedule reliability, port rotations and unscheduled calls, and how much capacity is deliberately cut, shape the price and downstream cost of a booking just as much as port performance.
Know which services deliver before you sign
With Far East to Europe at 4% on-time and a 43pp spread across carriers, the tender decisions you make now depend on knowing which services actually deliver. Xeneta Ocean Schedules gives you port pair, service and carrier reliability data, updated monthly, so you can benchmark your lanes before you commit.